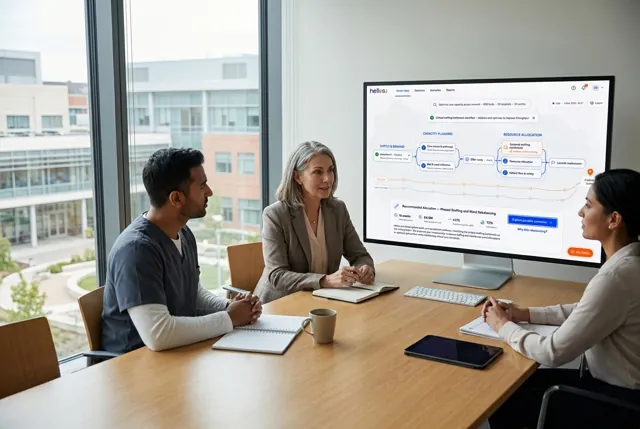
An underwriting director and actuary evaluating coverage, capital and pricing options at a desktop workstation. Illustrative generated scene.
Helios for Insurance

what’s next?

Risk is changing. Should every premium change too?

The Helios Experience

Balance coverage, capital and customer outcomes.
You define the outcome. Helios finds the path.

← All industries

Balance coverage, capital and customer outcomes.

Pricing changes affect the people in your book, not just its margin. Compare underwriting, reserving and reinsurance choices under different loss and retention scenarios.

Meet Helios Brain

01Coverage and underwriting rules

02Reserve and capital limits

03Fairness and affordability

Explore the Helios experience

Insurance
Helios BrainDEMO

AI-generated, hypothetical plans. No live business data, verified professional advice or real actions.

Do not enter sensitive information. Prompts are processed by AI and temporarily retained for this demo.

Choose a question or write your own goal0/5 steps connected
  1. 01
    Define the outcome
  2. 02
    Connect dependencies
  3. 03
    Compare routes
  4. 04
    Check constraints
  5. 05
    Human approval
Choose a question or enter your goal.The AI will create five steps and three distinct routes.
RecommendedBalanced path
AI-proposed timing
Awaiting AI
Referenced constraints
Awaiting AI map
Approval
Pending
ClearPressureBlockedAssumptionDependencyApproval gateEvidence

From underwriting strategy to evidence on the ground.

Pricing and capital choices belong to accountable insurance leadership. Claims and service teams add the observations needed to keep those choices grounded.

Decision authority

Underwriting, actuarial & risk leadership

Approve pricing and underwriting policies, reserving decisions and reinsurance structures through the relevant governance bodies.

Helios supports

Compare coverage, capital, retention and fairness trade-offs.

An insurance assessor capturing property evidence with a handheld tablet. Illustrative generated scene.
Claims assessors & case reviewers
Tablet in the field

Evidence travels. Authority stays explicit.

An assessor can capture conditions and review relevant policy context. Material coverage or settlement exceptions follow an authorized review path.

Appropriate scope
Gather evidence and handle cases within documented delegation limits.
Review & escalation
Authorized claims or underwriting reviewers for exceptions.
Evidence returned
Observed losses, supporting evidence, settlement outcomes and emerging patterns.
Illustrative ecosystem and interfaces, not a live deployment. Roles, integrations and approval limits are defined with each organization.

See the options. Understand the consequences.

01

Understand pricing and retention trade-offs

Ground the comparison in your data, your objective and your constraints.

02

Stress-test reserve assumptions

Make dependencies and assumptions visible before you commit.

03

Compare reinsurance structures

Carry the chosen path into a plan your team can review and act on.

The decisions worth rehearsing.

Potential applications, scoped to your data, priorities and operating environment.

01

Pricing strategy under multiple scenarios

Test pricing changes against your actual policyholder base. See who is affected, how retention shifts, how risk pools change. Identify the strategy that holds margin without abandoning customers.

02

Underwriting policy updates

Run new underwriting criteria against historical applications. See who would have been declined. Identify systemic biases before they become regulatory cases.

03

Claims reserve modeling

Stress-test reserve adequacy against catastrophic scenarios. See where the gaps are. Adjust capital allocation before the gap becomes a crisis.

04

Product launch evaluation

Before launching a new product, project adoption, claims patterns, and profitability across customer segments. Find the products that build long-term value versus those that look good in year one.

05

Reinsurance program optimization

Test alternative reinsurance structures against your loss distribution. See cost, coverage, and counterparty exposure trade-offs. Identify the structure that protects capital without overpaying for tail risk.

06

Distribution channel strategy

When shifting between agents, brokers, direct, and digital channels, simulate the impact on customer mix, retention, and lifetime value. See which channels truly grow the book versus which merely move existing business at higher cost.

07

Climate and catastrophe modeling

Integrate climate science into pricing and reserving. Test exposure under multiple climate scenarios across geographies. Identify the lines and regions where current pricing no longer reflects the underlying risk.

A useful pilot starts with the right foundations.

Agree a bounded decision, a baseline and acceptance criteria before introducing operational use. Scope and timing depend on your data, governance and intended application.

The data
  • De-identified policy, claims and exposure history
  • Reserving, coverage and capital rules
  • Prior pricing decisions and customer-impact assessments
The people
  • Underwriting and actuarial sponsor
  • Risk, claims and policy-data specialists
  • Compliance and customer-outcome reviewers
The evaluation
  • Sensitivity across agreed loss scenarios
  • Capital, coverage and fairness constraint checks
  • Traceability of recommendations to policy evidence
Before operational use
  • Validated actuarial assumptions and lawful data use
  • Named policy and exception authorities
  • Controlled versioning, monitoring and rollback

Knowing when to stop is part of the decision.

Missing evidence, uncertain conditions and absent authority require different responses. A recommendation must not silently become an action.

The signal

Loss or exposure data is not validated.

Appropriate response
Request reconciliation before advancing a pricing path.
Responsible review
Actuarial and exposure-data owners
Before the path resumes
The relevant loss and policy evidence is reliable.

Your rules are part of the model.

Regulatory context shapes how a system should be designed and reviewed. Your legal, compliance and domain teams remain part of that process.

Solvency II capital adequacy and ORSA requirements

EU AI Act high-risk classification for life and health pricing

Anti-discrimination law in underwriting and claims

IFRS 17 reserve disclosure and audit trail

Context for implementation, not a certification or guarantee of regulatory compliance.

Trust and governance

Start with the decision that matters to you.

The outcome, the boundaries and the people responsible. A focused starting point for a conversation about your organization.

Use high-level descriptions only. Do not include confidential, personal, patient, financial-account or classified information.

  1. 01The outcome
  2. 02The constraints
  3. 03The people
  4. 04Your details

The outcome

0 / 2000